Get Paid Early: Cash Advance

Screenshots
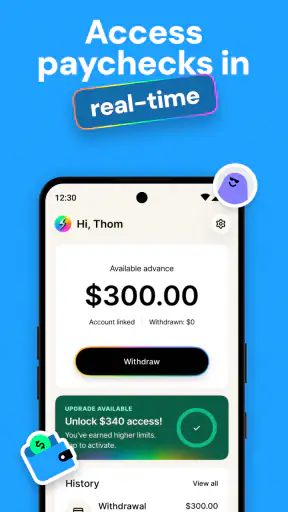
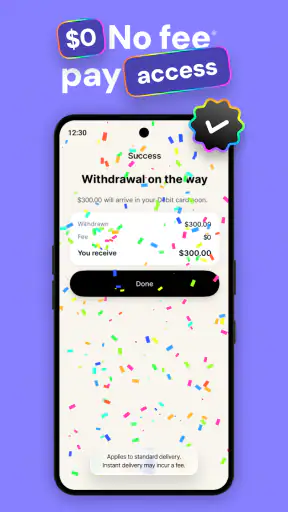
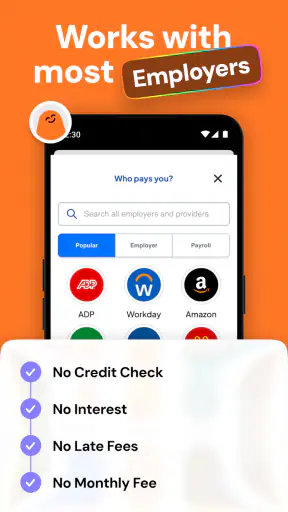
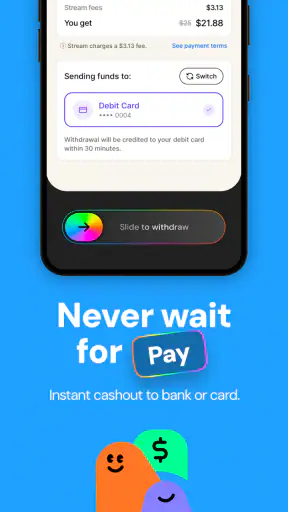
Details
- Rating
- 167.00 reviews
- Version
- 3.0.39
- Developer
- StreamFunds, Inc.
Analysis by Norviv
Getting paid before your regular payday can sound simple, but the details matter when money is tight. I approached Get Paid Early: Cash Advance as a first-time user would: looking for a quick way to handle a short gap without turning that gap into a larger financial problem. The app belongs to the finance category and is developed by StreamFunds, Inc. Its central idea is straightforward: help eligible users access pay they have already earned, rather than presenting the service as a conventional loan.
That distinction is the first thing I would keep in mind. This is not a budgeting app, a savings planner, or a replacement for a bank account. It is designed around timing. If your pay is on the way but an important bill, grocery trip, transport cost, or household expense arrives first, the app may fit that particular situation. If you need long-term help managing debt or regularly spend more than your income, it is probably not the tool I would choose.
What to expect before you request early pay
The store summary focuses on access to earned pay with no loans, no interest, and no hidden fees. In practical terms, that makes the app feel different from a credit card or payday lender. You are not approaching it primarily to borrow against a future income stream; you are trying to bring forward money connected to work you have already completed. That can make the idea easier to understand, especially for someone who wants to avoid interest-based borrowing.
Still, “early” does not mean that every request will solve an emergency instantly. The experience depends on whether the service can recognize your situation and whether the timing works for the payment you need to make. I would install it with a specific, modest use case in mind rather than assuming it is an unlimited emergency fund. That mindset helps prevent the app from becoming a routine substitute for a paycheck.
The app is free to install and carries an Everyone age rating, which makes the initial barrier low. Its current version is 3.0.39, and it supports devices running Android 7.0 or later. I would still make sure the phone is updated enough before beginning, because an older device can make any finance-related setup feel more confusing than it needs to be.
There is also some useful social proof without treating it as a guarantee. The app has an average rating of 4.2 from over 700 ratings, along with more than 160 written reviews, and it has passed 50 thousand installs. I read those figures as evidence that people are trying the service, not as proof that every employment or payment situation will work identically.
Who is most likely to find it useful?
I see the strongest fit for someone with a regular income who occasionally faces a mismatch between when work is completed and when money becomes available. Imagine finishing a workweek while a utility bill is due before the normal deposit arrives. In that situation, bringing forward part of earned pay could be more sensible than putting the bill on a high-interest card, provided the following payday remains manageable.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
It may also suit people who prefer a focused solution instead of opening a new credit account. The appeal is not just speed; it is the possibility of avoiding interest and keeping the request tied to earned income. That can be reassuring when the alternative is a short-term loan whose cost becomes difficult to track.
I would be more cautious if your income changes sharply from week to week, if your employer or work arrangement is difficult to verify, or if you are already relying on early access every pay cycle. The service may still be worth exploring, but it should not be treated as a promise of approval. More importantly, repeated advances can leave the next payday feeling smaller, even when the original request seemed harmless.
Setting up the app without rushing through the important parts
My advice for the first launch is to treat setup as a financial check, not as a formality. Read each screen carefully, especially anything connected to your employment, income timing, identity, or where funds may be delivered. Finance apps often require accurate information to match a user with the service, and entering a rushed estimate can create more delay than taking a few extra minutes.
Before you begin, have the basic information you normally use to confirm your work and pay arrangement close at hand. I would also use a private connection and avoid completing a financial setup on a shared device. Those are simple habits, but they matter more here than they would in a casual entertainment app.
One practical tip is to decide in advance how much you genuinely need. Do not start by asking, “How much can I get?” Start with, “What exact expense am I trying to cover?” That change in wording is useful because it turns the app into a controlled cash-flow tool. If the expense is a grocery trip, calculate the grocery amount. If it is a bill, use the bill total rather than taking extra money simply because it appears available.
Another useful habit is to check your next payday before completing a request. Write down the expenses that will already be waiting then. Early access can remove pressure today while creating pressure later, so the right question is not only whether the app can help now. It is whether the repayment timing or reduced upcoming pay will still leave room for rent, food, transport, and other essentials.
The first successful action
For a first meaningful result, I would choose a small, clearly defined need and work through the app slowly. The goal is to understand the complete path from eligibility to receiving early pay, not to maximize the first request. Keep the purpose of the money visible while you move through the screens, and save any confirmation details that explain what happens next.
This is also where expectations should stay realistic. The app’s promise is about accessing earned pay, not about creating new income. If the money is needed because your monthly spending is consistently higher than your earnings, an early-pay service can only move the timing around. It cannot repair that underlying gap. In that case, a conversation with your employer about pay scheduling, a basic spending plan, or a lower-cost banking option may be more useful over time.
I would not judge the whole experience solely by how quickly the first screen responds. A responsible financial workflow may include checks that feel slower than tapping through a social app. What matters is understanding what stage you are in, whether the request has been accepted, and when the money should be available. Keep notifications enabled if you rely on the app for an important bill, but do not assume a notification itself means the funds have already reached your account.
A small but important workflow improvement is to use the app alongside your regular payday calendar. After a successful request, mark the expected effect on your next pay period. This makes the advance visible instead of letting it disappear into everyday spending. I find that this simple record is one of the best ways to stop a convenient feature from becoming invisible recurring debt.
Points that can confuse a first-time user
The phrase “no loans” can be reassuring, but it should not be interpreted as “no financial consequences.” Even when interest is not involved, receiving money early changes the timing of your income. Your future deposit may be smaller or your available pay may be affected by the amount you brought forward. I would always read the final confirmation carefully and make sure I understand the effect on the next pay cycle.
“No hidden fees” is another phrase worth reading precisely. It tells me the service is presented without hidden charges, but I would still examine every confirmation screen for the exact terms of the action I am taking. A user should know whether the request is optional, how it is completed, and what account or pay arrangement is connected to it. Skipping those details is the easiest way to feel surprised later.
Another common misunderstanding is expecting the app to function like a general-purpose wallet. Its purpose is narrower. You should not install it expecting bill negotiation, investment guidance, credit repair, or a full spending dashboard. Its value comes from helping with access to earned pay; the more your needs move away from that task, the less relevant it becomes.
Eligibility is also something I would approach carefully. A person can have a genuine need and still find that the app cannot complete the process for their particular income or employment setup. That is not necessarily a sign that the app is broken, but it does mean you should keep a backup plan for an urgent payment. Never wait until the final hour before a bill is due to discover whether a financial service works for you.
If you are wondering whether the app is suitable for someone under eighteen, the Everyone rating describes the content level rather than guaranteeing access to every financial function for every person. I would follow the service’s own requirements and use it only in a legitimate adult financial context. The rating should not be read as permission to bypass identity or income checks.
How it compares with familiar alternatives
Compared with a credit card, the main advantage is the possibility of avoiding interest and keeping the request linked to earned pay. A credit card is more flexible for purchases and may offer a longer repayment structure, but that flexibility can encourage a balance to linger. I would choose the app for a short timing gap and a card only when I had a clear plan to pay the statement without carrying expensive debt.
Compared with a payday loan, the stated no-loan and no-interest approach is much more appealing to me. Payday loans can make a small emergency expensive, particularly when a borrower rolls the balance forward. That does not make early-pay access automatically harmless; it simply means the cost structure and timing need to be understood before use.
Compared with an overdraft, the app may be preferable when you know an expense is coming and want to arrange access before your account falls below zero. An overdraft is often reactive: the charge happens first, and the account problem appears afterward. Early access can be more deliberate, but a bank’s overdraft protection may still be more useful for an unexpected transaction that cannot wait for an app workflow.
Compared with asking an employer for a payroll adjustment, the app may be more convenient for an occasional need, while an employer conversation could be better if the timing problem happens every pay period. The employer route may address the source of the delay rather than repeatedly managing its symptoms. I would consider both options instead of assuming one must replace the other.
My practical recommendation for using it responsibly
I would recommend beginning with one planned request, not making the app part of every payday routine. Keep the amount connected to a necessary expense, review the impact on the next deposit, and avoid using early pay for impulse purchases that could wait. This approach lets you test whether the service fits your real cash flow without immediately building a habit around it.
It is also worth separating convenience from reliability. A finance app can make a process feel easy, but easy access can reduce the pause that normally makes us question a purchase. I would add that pause manually: name the expense, check the next payday, and ask whether another option costs less or creates fewer future obligations. That three-step check is more valuable than simply tapping through quickly.
If the app works well for you, keep your expectations narrow. Use it as a bridge for earned income, not as a financial safety net that grows whenever your budget is short. If it does not fit your employment situation, do not keep forcing the setup or repeatedly applying without understanding why. A conventional savings buffer, direct payroll change, bank overdraft arrangement, or carefully managed credit option may be better depending on your circumstances.
My overall impression is favorable for the specific problem it targets. Get Paid Early: Cash Advance offers a clear alternative to borrowing with interest when the issue is simply that earned money has not arrived yet. The free app, Everyone age rating, broad device compatibility, and growing user base make it approachable for a first look, while the strongest benefit is the focus on timing rather than conventional lending.
I would recommend it to a person who has stable earned pay, a temporary cash-flow mismatch, and the discipline to check what early access means for the next payday. I would skip it if I needed long-term debt help, had no reliable income connection, or was looking for a full money-management system. Used deliberately, it can be a useful bridge. Used automatically, it can merely move the same problem forward.
The best next step is simple: install it only when you can identify the expense, review the setup information carefully, and make your first request small enough to understand comfortably. That gives you a meaningful test of the service while keeping control of the decision in your hands.
Frequently Asked Questions
01What is Get Paid Early: Cash Advance, and how does it work?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected income before their regular payday. After creating an account and completing the required verification, the app may review information such as income and employment details to determine eligibility. Approved users can request an advance, review the applicable terms, and receive funds according to the available delivery options.
02Who can use Get Paid Early: Cash Advance?
Eligibility depends on several factors and may vary by location, employment situation, income pattern, and other information used during the application process. Users generally need to be adults with a supported bank account and a verifiable source of recurring income. Installing the app does not guarantee approval, and the service may not be available in every state, country, or to every type of worker.
03How much money can I request, and how quickly will I receive it?
The amount available through Get Paid Early: Cash Advance is determined individually rather than being the same for every user. Your approved limit may depend on income, account history, repayment behavior, and other eligibility checks. Delivery time can also differ: standard transfers may take longer, while an optional faster delivery method may involve an additional fee. Always confirm the final amount and timing before accepting.
04Does Get Paid Early: Cash Advance charge fees or interest?
Costs depend on the advance and delivery option selected. Some services may not charge traditional interest, but they can apply membership fees, expedited-transfer fees, or other charges. Before requesting money, carefully review the complete disclosure showing the amount you will receive, the total repayment amount, recurring subscription costs, and any optional charges. Terms can change, so rely on the in-app agreement rather than assuming the service is free.
05What should I consider before using a cash advance app?
A cash advance can help cover a short-term emergency, but it should not replace regular budgeting or serve as a long-term borrowing solution. Review the repayment date, automatic debit authorization, subscription terms, and possible fees before proceeding. Make sure enough money will remain in your account when repayment is due, because repeated advances or unsuccessful withdrawals could create additional financial pressure or bank charges.


